Smarter Generosity: How Tax-Advantaged Giving Vehicles Can Deepen Your Charitable Impact
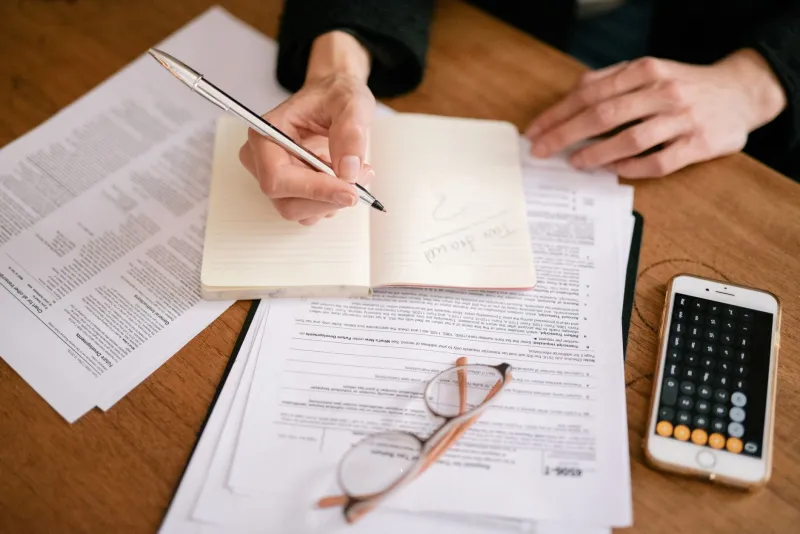
For many Americans, the weeks between Thanksgiving and New Year's Eve represent something far more significant than holiday celebrations. They mark the final opportunity to align financial planning with philanthropic purpose — a window during which the right decisions can simultaneously reduce a tax burden and meaningfully support communities in need. At Balaji Charitable Trust, we believe that informed generosity is empowered generosity. Understanding the landscape of tax-advantaged charitable vehicles is not about gaming the system; it is about ensuring that more resources reach the people and programs that need them most.
Why the Year-End Calendar Matters for Donors
The U.S. tax code, while notoriously complex, contains a number of provisions specifically designed to reward charitable behavior. Most of these provisions operate on a calendar-year basis, meaning that donations must be completed by December 31 to count toward the current tax year. For donors who itemize deductions, this deadline carries real financial weight. For those who do not itemize — now the majority of American taxpayers following the 2017 Tax Cuts and Jobs Act — there are still powerful strategies worth exploring.
The key is to begin planning well before the holiday rush. Decisions made in October or November tend to be more deliberate and impactful than those made in the final days of December under time pressure.
Donor-Advised Funds: Flexibility Meets Intentionality
Few giving tools have grown in popularity as rapidly as the donor-advised fund, or DAF. In essence, a DAF functions like a charitable savings account. A donor contributes cash, securities, or other assets to a sponsoring organization — typically a community foundation or a financial institution's charitable arm — and receives an immediate tax deduction. The funds are then invested and grow tax-free until the donor recommends grants to qualified nonprofit organizations of their choosing.
What makes DAFs particularly appealing is their flexibility. A donor can contribute a large sum in a high-income year to capture the maximum deduction, then distribute grants to charities over the following months or even years. This approach is especially useful for individuals who experience irregular income — business owners, executives receiving bonuses, or professionals in commission-based fields.
For donors who have appreciated stocks or mutual fund shares, contributing those assets directly to a DAF rather than selling them first can be especially advantageous. By doing so, the donor avoids capital gains tax on the appreciation while still receiving a deduction based on the full fair market value of the asset.
Qualified Charitable Distributions: A Powerful Tool for Retirees
Americans aged 70½ or older who hold traditional IRAs have access to one of the most tax-efficient giving mechanisms available: the Qualified Charitable Distribution, or QCD. Under this provision, individuals may transfer up to $105,000 per year (as of 2024, with annual inflation adjustments) directly from their IRA to a qualified charitable organization without the distribution being counted as taxable income.
This matters enormously for retirees who do not itemize deductions and who are subject to Required Minimum Distributions (RMDs). By directing some or all of an RMD to charity via a QCD, a retiree can satisfy the distribution requirement, reduce their adjusted gross income, and potentially lower their Medicare premiums — all while supporting causes they care about deeply.
It is worth noting that QCDs must go directly from the IRA custodian to the charitable organization. Funds withdrawn first and then donated do not qualify. Donors should consult their financial advisor or IRA custodian well in advance of year-end to ensure the transfer is processed in time.
Bunching: Making the Most of the Standard Deduction Era
Since the standard deduction nearly doubled under the 2017 tax reform — reaching $14,600 for single filers and $29,200 for married couples filing jointly in 2024 — fewer Americans find it financially worthwhile to itemize. This has led many donors to feel that the tax benefit of charitable giving has diminished.
The "bunching" strategy offers a practical workaround. Rather than giving a consistent amount each year, a donor consolidates two or more years' worth of charitable contributions into a single tax year, pushing their total deductions above the standard deduction threshold. In the alternate years, they claim the standard deduction. When combined with a DAF, this approach is particularly elegant: the donor makes a large contribution to the DAF in a bunching year, captures the deduction, and then distributes grants to their chosen charities on whatever timeline they prefer.
Charitable Remainder Trusts and Other Planned Giving Options
For donors with more substantial assets and longer time horizons, planned giving instruments such as Charitable Remainder Trusts (CRTs) offer an additional layer of sophistication. A CRT allows a donor to transfer appreciated assets into an irrevocable trust, receive a partial charitable deduction, and draw an income stream from the trust for a specified period. Upon the trust's termination, the remaining assets pass to designated charitable organizations.
While CRTs require more legal and financial infrastructure than a DAF, they can be an excellent fit for donors approaching retirement who hold highly appreciated real estate or business interests. Similarly, charitable lead trusts, bequests, and life insurance policies naming a nonprofit as beneficiary all represent meaningful ways to extend philanthropic impact beyond one's lifetime.
Choosing the Right Vehicle for Your Situation
No single giving strategy suits every donor. The right approach depends on a combination of factors: age, income level, asset composition, tax filing status, and the nature of the charitable causes a donor wishes to support. A 35-year-old technology professional with concentrated stock holdings faces a very different set of considerations than a 72-year-old retiree drawing down IRA assets.
At Balaji Charitable Trust, we encourage donors to approach these decisions as an integrated part of their broader financial planning — ideally in consultation with a qualified tax advisor or certified financial planner who has experience with charitable giving strategies. The goal is not complexity for its own sake, but clarity: understanding precisely how each dollar given can be multiplied in its effect on communities that depend on philanthropic support.
Turning Planning Into Purpose
Tax efficiency and genuine generosity are not in conflict. When donors understand the tools available to them and use those tools thoughtfully, the result is a more sustainable culture of giving — one in which resources flow more reliably to organizations doing essential work in communities across the country.
As the year draws to a close, we invite you to consider not just how much you can give, but how strategically you can give. The communities served by Balaji Charitable Trust and organizations like it are counting on donors who treat philanthropy not as an afterthought, but as a deliberate, informed, and deeply human act of commitment to a better world.